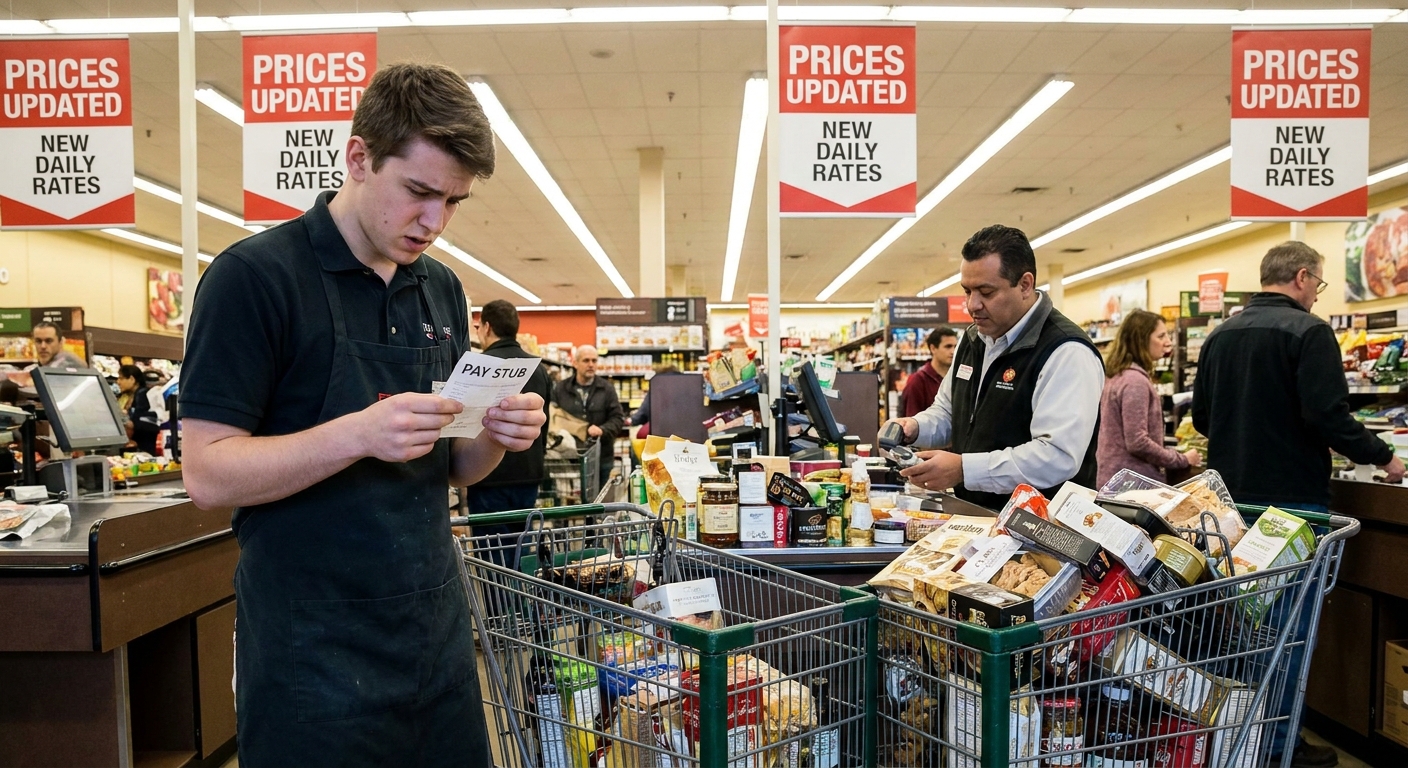
American workers are facing a new kind of squeeze: wage growth is slowing just as many household bills remain stuck at higher levels.
Why Your Paycheck Suddenly Feels Smaller
Government data show average hourly earnings were up about 4.0% year‑over‑year in late 2024–2025, down from peaks above 5–6% in 2022. At the same time, inflation—while off its highs—has settled around 2.5–3.5%, depending on the month and the measure.
On paper, that means workers are finally seeing “real” wage gains again (pay growing faster than prices). But because prices jumped so sharply during 2021–2023, many households feel like they’re running in place. Groceries, rents, and childcare didn’t go back down; they just stopped rising as fast.
If your paycheck feels like it doesn’t go as far, you’re not imagining it. The gap between the cost of living and pay levels that lagged during the inflation spike is still being closed.
What’s Actually Happening With Wages
1. Wage growth is slowing but still elevated
- Average hourly earnings: roughly 4.0% annual growth.
- Pre‑pandemic norm: closer to 2.5–3%.
- 2021–2022 peak: 5–6% annual wage increases.
Employers are no longer raising pay as aggressively as they did when they were desperate to hire post‑pandemic. But they haven’t fully returned to the old slow‑growth pattern either.
2. Job openings are down, bargaining power is shifting
The ratio of job openings to unemployed workers has drifted from about 2 openings per job seeker at the peak of the labor crunch, closer to 1.2–1.4.
That shift matters for your paycheck:
- Fewer open roles = less leverage to demand big raises.
- Hiring is more selective, especially in tech, finance, and remote‑friendly office jobs.
- Front‑line and service roles still see decent competition, but signing bonuses and fast raises are less common.
3. Inflation is lower—but not low compared with pre‑2020
Year‑over‑year inflation has cooled from over 8–9% in 2022 to around 2.5–3.5%. But prices are cumulative:
- A $250 weekly grocery bill that rose 15–20% over two years may now rise only 2–3% a year—but it’s not going back to $210.
- Rents that jumped 20–25% in some cities are now ticking up more slowly, but remain at the higher level.
So even with wages now rising slightly faster than prices, workers are still trying to climb out of a deep hole.
What This Means for Your Budget
Paychecks vs. prices: the real wage story
Real wages (pay adjusted for inflation) are finally inching up, but the gains are modest:
- If your pay rose 4% in the past year and your personal inflation (your actual mix of rent, food, gas, childcare) was 3%, your real income only grew 1%.
- On a $60,000 salary, that’s just $600 more purchasing power per year—or $50/month.
That doesn’t feel like much when:
- Your rent is up $250/month since 2021.
- Your grocery bill is up $80–$120/month.
- Childcare or after‑school programs cost $100–$200 more a month.
Mortgages and housing
If you bought or refinanced when mortgage rates were around 3%, you’re relatively insulated on housing costs. If you’re in the market now:
- 30‑year fixed rates have hovered around 6–7%, roughly doubling borrowing costs compared with early 2021.
- On a $400,000 mortgage, the difference between 3% and 6.5% can be about $800–$900 more per month.
With wage growth slowing, stretching to buy at elevated prices and rates is riskier. Lenders are stricter, and your debt‑to‑income ratio matters more.
Debt and credit cards
The Federal Reserve’s push to fight inflation kept short‑term interest rates high longer than many expected:
- Average credit card APRs have run above 20%, often 23–27%.
- A $5,000 balance at 24% costs roughly $100/month in interest alone if you only pay the minimum.
With wages not surging the way they were in 2021–22, carrying expensive debt eats away at the modest real gains you might be seeing in your pay.
Why Wage Growth Is Cooling
1. The Fed’s inflation fight is working—at a cost
The Federal Reserve raised its key interest rate from near 0% to more than 5% in under two years. Higher borrowing costs:
- Slow business expansion and hiring plans.
- Make employers cautious about adding staff or offering aggressive raises.
- Cool demand in rate‑sensitive sectors: housing, autos, construction, some business services.
This is by design: a cooler labor market is part of how inflation comes down. But it also means your bargaining power at work is weaker than it was a couple of years ago.
2. Productivity and profits shape pay decisions
Wages tend to rise faster when workers are producing more per hour and when corporate profits are robust.
- Some sectors (tech, logistics, professional services) boosted productivity with automation and software, then used layoffs and hiring freezes to protect margins.
- Other sectors (health care, education, hospitality) have struggled with staffing and burnout, but face budget limits or thin margins.
The result: many firms are focusing on targeted raises and bonuses, not broad big pay bumps.
3. The job mix is changing
Higher‑paying sectors like tech and finance have cooled hiring, while lower‑wage service sectors continue to add jobs. That mix pulls average wage growth down, even if some individuals are still getting solid raises.
Practical Moves for Households Right Now
1. Audit your real wage, not just your raise
Calculate your personal inflation rate:
- Compare last year’s monthly spend on rent/mortgage, groceries, gas, childcare, insurance, debt payments to this year’s.
- If your total spending rose 5% and your income rose 3%, you effectively took a 2% pay cut in real terms.
Use that number to set savings and spending targets.
2. Prioritize high‑interest debt
With wage growth cooling and card APRs above 20%:
- Treat any balance over 8–10% interest as an emergency.
- Consider a 0% balance transfer card (if your credit allows) or a personal consolidation loan in the single‑digit range.
- Aim to free at least $100–$200/month from discretionary spending to attack these balances.
3. Get strategic about raises and job changes
In a cooler labor market:
- Raises within your current job may still range 3–5% if you can demonstrate impact.
- Job‑hopping pay bumps that were 15–25% in 2021–22 may look more like 5–10% now.
Use data:
- Check salary benchmarks (BLS, Glassdoor, Levels.fyi, industry surveys).
- Prepare a concrete case: revenue you influenced, costs you cut, projects you led.
4. Protect your emergency margin
With uncertainty about where wages and the job market go next, aim for:
- 3–6 months of essential expenses in cash or a high‑yield savings account.
- Automatic transfers—even $50–$100 per paycheck—to build that cushion.
5. Plan around your “floor” income
Instead of budgeting off your best‑case scenario (overtime, bonuses, side gigs), plan using your base, guaranteed pay. Treat variable income as extra to:
- Pay down debt faster.
- Rebuild savings eroded by inflation years.
- Invest for retirement.
The Bottom Line for Your Household
Wage growth is no longer sprinting ahead, but prices are still anchored at a higher plateau after a historic inflation shock. Many families are seeing only slim real gains—or still catching up.
The most effective response is not panic, but precision: know your real wage, cut the highest‑cost leaks in your budget, be deliberate about career moves, and rebuild financial buffers. The paychecks may not be shrinking, but the room for error in your household finances is.